Should you refinance your mortgage?
Refinancing replaces your current mortgage with a new loan. Whether it makes sense depends on your goals, the costs and how long you expect to keep the loan.
Start with what you want to achieve
Compare refinancing with keeping your current mortgage. Your goal may be a different payment, a shorter repayment period, a more predictable rate or access to equity for renovations or other needs when eligible.
Look at the overall result. A lower monthly payment does not always mean a lower overall cost.
Explore your refinancing options
Use this overview to start your conversation. FHL Mortgages can help you compare the routes available for your existing loan and goals.
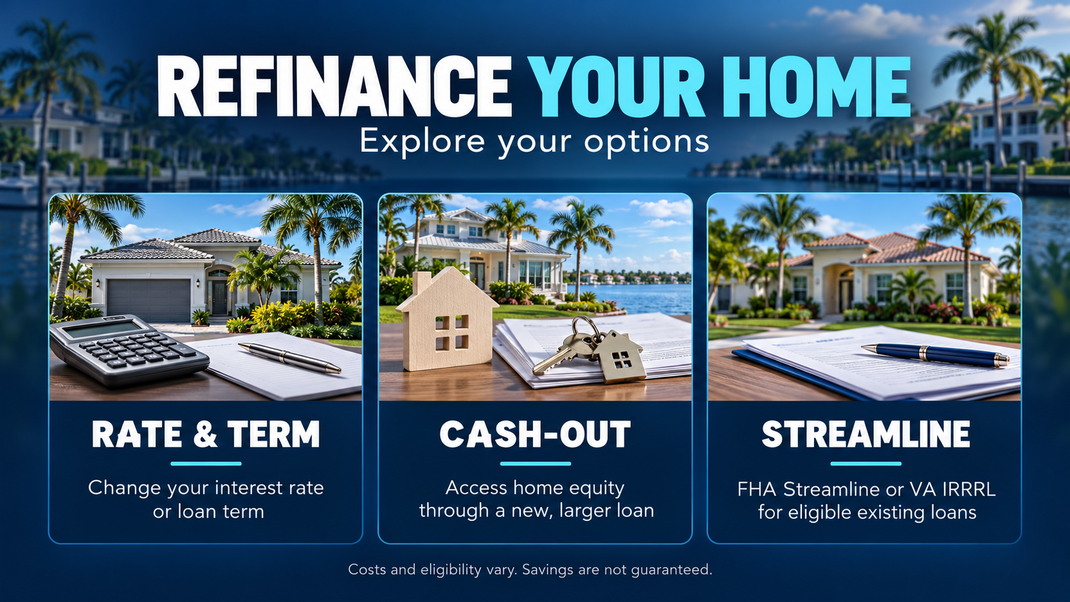
Confirm the details for your loan. Eligible costs and limited incidental cash on a no cash-out refinance follow program rules. Cash-out proceeds are determined after the existing loan and transaction costs are addressed, subject to equity and program limits; pricing may differ from no cash-out refinancing.
Consider alternatives and risk. Compare a HELOC or home equity loan where available, and ask about renovation financing for projects. Cash-out proceeds are borrowed money secured by your home. If consolidating debt, consider the risk of securing previously unsecured balances against your property.
Understand refinance costs
Request a written Loan Estimate. Refinancing may offer financial benefits but can involve several thousand dollars in costs. Compare the expense with your short- and long-term goals. Actual charges vary by loan, lender, property and location.
Lender and property charges. These may include origination, processing or underwriting; appraisal and credit report; and tax service or survey when required.
Closing charges. Allow for title and settlement, applicable attorney charges, recording charges and applicable taxes.
Other funds. Plan for prepaid interest, initial escrow funding, discount points and program-specific charges where applicable.
Review how costs are paid
Ask what “no-cost” covers. Lender credits may offset charges in exchange for a higher rate. Alternatively, eligible costs may be added to the loan balance. These are different arrangements; neither necessarily eliminates the expense.
Compare discount points. Points can reduce your rate in exchange for an upfront cost. Compare offers with and without points, considering pricing, savings and how long you expect to keep the loan. Points are not automatically worthwhile or unsuitable.
Estimate your break-even period
For a simple payment-savings comparison:
Relevant refinance costs ÷ monthly savings = approximate months to break even
Use the shortcut carefully. It does not capture all differences in repayment term, balance or total interest. Separate actual fees from escrow deposits and prepaid expenses.
Compare repayment terms
A shorter term may increase the payment while reducing interest over time.
A longer term may lower the payment while increasing total interest.
Use your remaining term as the starting point. Compare the new loan with the repayment period left on your current mortgage, rather than only comparing original loan lengths.
Compare lenders and loan details
Use matching assumptions. You can refinance with your current lender or another lender. Compare written Loan Estimates using the same loan amount, repayment term and rate-lock assumptions.
Ask practical questions. Which charges can change? What documentation is needed? Does the new payment include taxes and insurance?
Prepare for closing
Review and arrange. Check your Closing Disclosure, required funds, identification and signing arrangements.
Confirm the timing. Ask about any applicable cancellation period, funding and payoff timing.
Keep payments current. Continue making required payments on your existing loan until its payoff is confirmed.
Compare before you refinance
Speak with FHL Mortgages to review your goals and compare available options with your current mortgage.
Educational information only; not an approval or commitment to lend. Savings, rates and eligibility are not guaranteed. FHL Mortgages is a DBA and mortgage department of Florida Homes & Loans Inc. | NMLS #2295908. Gemma Peterson | NMLS #2121526. Request secure upload instructions before sharing financial documents.